Atradius Atrium
Get direct access to your policy information, credit limit application tools and insights.

 United Kingdom
 Australia
 Austria
 Belgium
 Brazil
 Bulgaria
 Canada
 China
 Czech Republic
 Denmark
 Finland
 France
 Germany
 Greece
 Group
 Hong Kong SAR
 Hungary
 India
 Ireland
 Italy
 Japan
 Lithuania
 Mexico
 Netherlands
 New Zealand
 Norway
 Poland
 Portugal
 Romania
 Singapore
 Slovakia
 Slovenia
 Spain
 Sweden
 Switzerland
 Turkey
 United Arab Emirates
United Kingdom
 United States
Our Q3 2026 Industry Highlights Report explores the trends shaping nine key UK sectors. Across the market, businesses continue to face higher costs, pressure on margins and ongoing geopolitical uncertainty. Consumer confidence remains subdued, while inflation continues to affect investment and growth across many industries.
Despite these challenges, opportunities remain. Businesses that invest in technology, sustainability and operational efficiency are often better placed to adapt and grow. We also see continued momentum in areas such as digital transformation, renewable energy and AI-driven innovation.
The construction sector remains challenging given the continued difficult market conditions. Core construction activity continues to be slow, with weak demand, and a thin pipeline of new projects.
For the 19th consecutive month, construction activity continues to shrink, according to Purchasing Managers’ Index (PMI). The reasons attributed to the continued shrinking are lack of new project starts, deferred investment decisions, and geopolitical tensions. One of the main concerns in the sector is that we are yet to see key impacts of cost inflation on currently ongoing projects, and the extent to which this impacts the appetite for starting new projects. We are mainly concerned with housebuilding and groundworks sub-sectors. The housing sector recently has been impacted by higher energy and output costs, weaker consumer confidence, stubborn interest rates and lack of government support. Whilst the groundworks sector is severely impacted by the lack of new project starts, alongside delays in project starts.
Our current underwriting approach in the short-term and long-term is cautious. At the start of the year we were more optimistic regarding the improvement of the sector, however, output in the construction sector is now expected to fall in 2026, and recovery may not occur until 2028. Any improvement will be slow and dependant on an improving economy as construction is cyclical with the UK economy, which has been performing particularly poorly over the last few years.
Any improvement in the sector will be slow, steady, and stable as is the norm in construction due to the type of contracts and projects.
The sector is undergoing a significant transition from fossil fuels towards low- carbon and renewable sources.
The sector has seen an increase in business failures compared with previous years, highlighting ongoing financial fragility within parts of the retail energy market. Refining capacity has weakened by the closure of one refinery and the failure of another, reducing the UK’s ability to process fuel domestically.
At the same time, the biodiesel manufacturing industry has faced increasingly difficult market conditions, driven by heavily subsidised imports from the US, UK policy support that has lagged behind European counterparts, and high operating costs. These pressures led to the closure of several biodiesel plants across the UK.
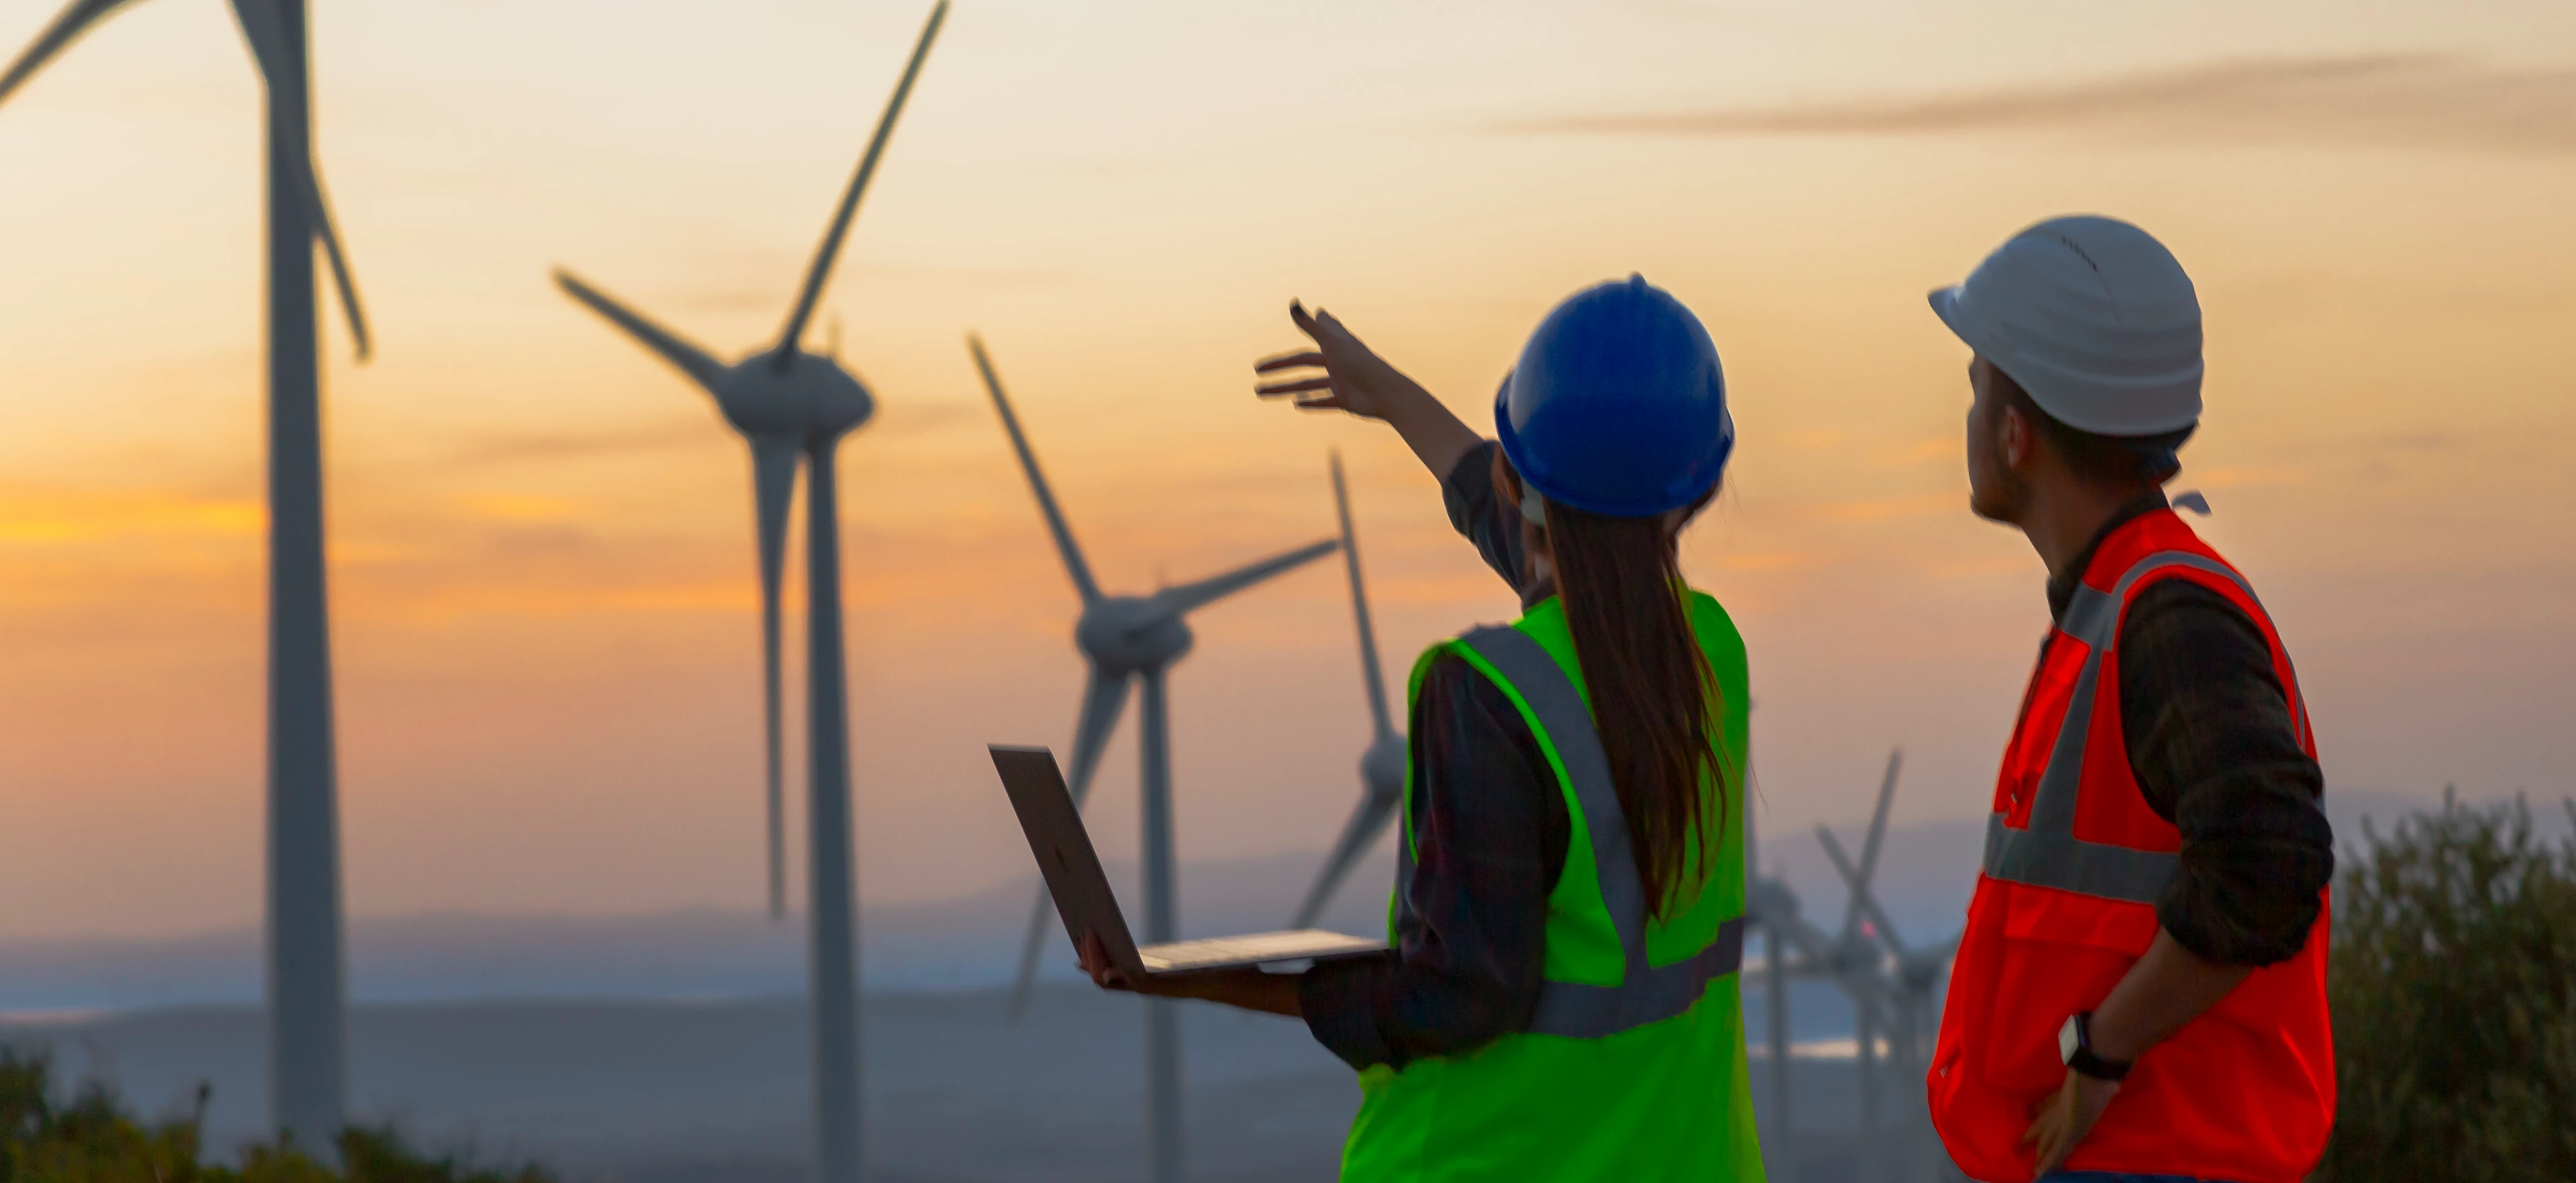
There is growth in the renewables sector with solar and wind farms seeing an increase in new projects. These are highly capex intensive projects, leading to high operating costs and higher financing costs. As more renewables come online there have been issues with grid connection queues lengthening. As a result, development is running at a slower pace.
The current Middle Eastern conflict continues to bring inflationary pressure globally. As a result, the UK has experienced rising wholesale oil prices feeding into energy bills, transport costs, and broader inflation. Atradius has successfully managed many complex situations in recent years, and our experience shows that maintaining a rigorous approach and working closely with our partners, brokers and customers is most effective. We continue to monitor developments.
Despite the challenges, claims have remained low over the past three years. We are actively working with customers to manage notable deterioration in risks, as such a case-by-case approach required where reduced buyer performance is notable.
The government’s long-term objective remains achieving net zero greenhouse gas emissions by 2050, with a target for a predominantly clean electricity system by 2030.
Modern Engineering techniques, with the adoption of new technology, continue to outperform the older traditional industry as we enter a definitive phase of Robotics for the UK.
Given the diverse nature of the industry, each buyer must not only be assessed on their merits, but also the type of manufacturing. Heavy, so-called traditional manufacturing, continues to face the brunt of the UK economic headwinds, as they are often energy intensive and environmentally challenging. Manufacturing of new tech, where we often find a high degree of research and development, bode for better opportunities. The provision of up-to-date management accounts allied to an overview of the business strategy remain key elements in our ongoing support of businesses.
Energy and raw material inflation continue to plague the sector, while stubbornly high inflation results in interest rates holding, perhaps, just above the level that may prove the economic catalyst. Volatility in raw material costs from the well-documented geopolitical events have continued to weigh heavy on the sector. In turn, this has reduced the margin attracted on several products. The conflict in the Middle East has also played a very significant impact as many chemicals are produced and shipped from the Middle East.
Heavy, so-called traditional manufacturing, continues to face the brunt of the UK economic headwinds.
We maintain a positive stance but are operating with increased caution, as the sector continues to grapple with both new and long-standing challenges.
Input costs for food and drink manufacturers have been elevated since the pandemic. Increasing in the last 12 months following higher employee National Insurance and Real Living Wage contributions, the conflict in Iran and a drought impacting Europe. High input costs and the reticence of large retailers to accept price increases, is squeezing profit margins. Sustainability is a core theme in investment, particularly around carbon reduction, biodiversity and soil health.
Food and agriculture are two of the best-placed industries to get on board with these, however the high cost of investment is a barrier for smaller businesses. Livestock-focused farms have benefited from strong farmgate prices and strong demand. Arable farming however, is under pressure due to weaker commodity prices and weather-related yield volatility.

Supply chain disruptions, such as the conflict in Iran or US tariffs, continue to challenge both industries, considering their reliance on commodities such as energy, fuel and fertilizer. Input costs and food price inflation are predicted to rise further in the next 12 months as the conflict remains unresolved. Consumer demand is projected to be resilient but increasingly value focused as food prices continue to rise. We continue to support cover where the financial profile supports it, and work closely with businesses where more insight is required.
The sector benefits from consistently high demand but continues to be challenged by diminished consumer spending power.
The sector benefits from strong demand driven by AI adoption, cloud migration, cybersecurity investment, and digital transformation.
We see traditional resellers evolving their offering by also providing managed services and consulting to support growth in this mature part of the sector. Investment in AI, cloud computing and data infrastructure remains a key growth driver, with increasing numbers of large-scale data centres being built. Cybersecurity spending is increasing as businesses respond to evolving cyber threats, regulatory requirements, and greater dependence on digital infrastructure. The cybersecurity market has demonstrated strong growth in both revenue and employment.
Demand for managed services, software, cloud migration and data analytics remains robust, particularly within regulated sectors such as financial services, healthcare and government. For those operating in low-value-added hardware and reseller segments, competitive pressures remain significant, leading to lower growth and increased M&A activity. Challenges include ongoing skills shortages, pressure on margins from wage inflation, increased competition, and caution around discretionary spend.
We maintain a positive outlook on the sector, and our underwriting stance remains supportive. Greater caution is applied to high-growth businesses where growth generally comes by significant debt-funded investment. And to companies displaying continued margin pressure, increased leverage, customer concentration, or weakening cash flows.
For those operating in low-value-added hardware and reseller segments, competitive pressures remain significant, leading to lower growth and increased M&A activity.
Strains for UK metals persist into Q3 2026 as interventionist policy measures compound with soft demand across core end markets.
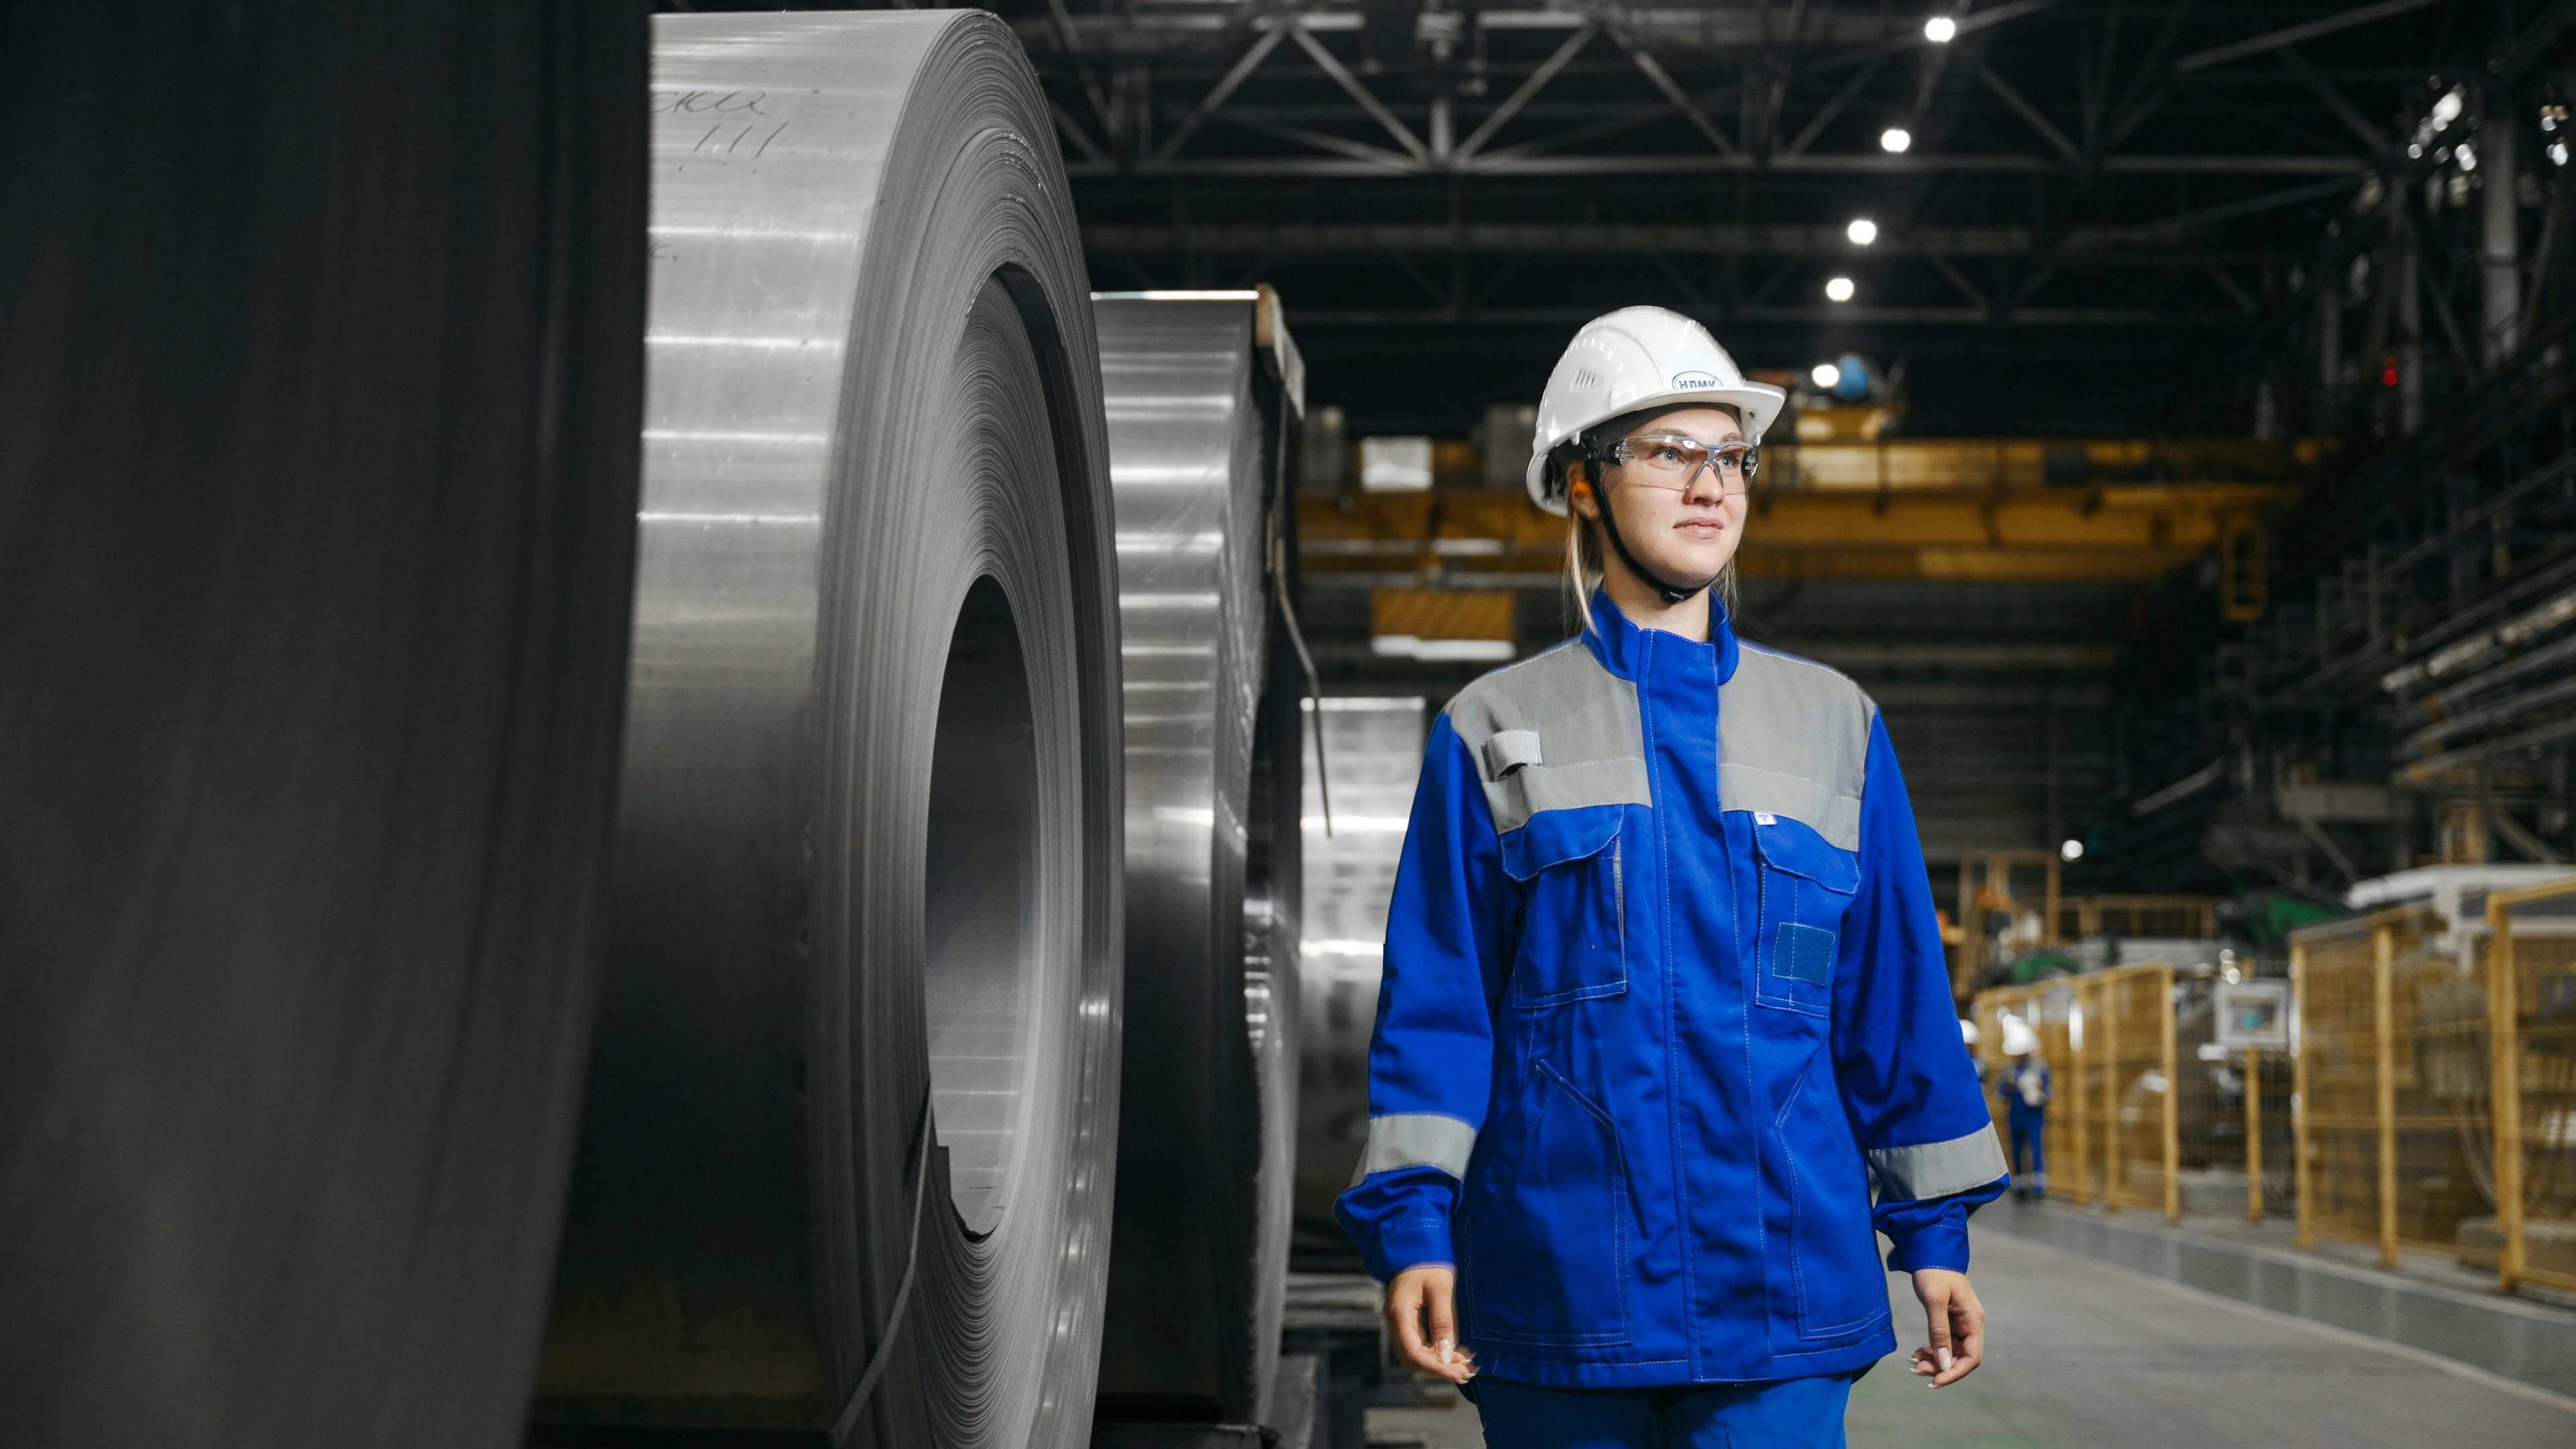
While tightened tariff rate quotas have nudged prices higher in recent months, they have also added pressure for UK importers who now face disrupted supply channels as well as additional charges on oversubscribed product categories. Front-loaded orders in the run up to the tariff change had already diminished liquidity reserves across the sector, and ongoing weak demand is now limiting some buyers’ ability to unwind working capital and, ultimately, to pass-through higher product costs.
Similar concerns were echoed by Duferco, who announced the recent wind-down of Meridian Steel whose primary feedstock is non-domestic. Domestic producers also carry their own burdens, with the recent nationalisation of British Steel emphasising ongoing structural issues of high energy costs, global overcapacity, and expensive capex requirements in the push for greener, decarbonised product offerings.
While many businesses are well positioned to endure, our underwriting remains tightly focused on margin and working capital controls. A tight handle on input costs and outsell pricing mechanisms is increasingly important. Import-reliant distributors, processors operating on thin margins, and those with significant exposure to niche construction projects continue to warrant caution.
Tightened tariff rate quotas have nudged prices higher in recent months.
Sustainability remains a key focus within the industry. ‘Circularity’ continues to be, and increasingly so, a greater feature and opportunity.
The UK paper and packaging market is being shaped by increased regulation, sustainability requirements, e-commerce growth, and the continued migration away from difficult-to-recycle plastics. This fuels growth in other products, with perhaps the traditional cardboard box remaining the most chosen option, as OCC (Old Corrugated Cardboard) can be widely recycled. The biggest industry development is the UK’s Packaging Extended Producer Responsibility (EPR) scheme. Under this scheme packaging producers face increasing fee structures linked to recyclability assessments. Packaging that is easier to recycle will attract lower costs, while complex multi-material packaging may incur higher charges. Products that are difficult to separate are likely to be at the higher end of the scale.
Our sector approach remain supportive, this is allowed by the notion that we have some very mature business which operate within the sector and therefore, we are furnished with management accounts on a frequent basis.
ESG targets are more of a discussion point, as we strive to understand how a business will cope and/or adopt to changing legal requirements.
UK high-street footfall is under significant pressure amidst record breaking heatwaves.
Consumer confidence remains persistently low, meaning retailers are having to work extremely hard to convince consumers to spend. Retailers are also facing mounting cost pressures from increases in National Living Wage and National Insurance contributions making it even more difficult to preserve adequate profit margins. As a result, we continue to see elevated levels of job losses, as businesses focus on reducing costs where possible. Summer heatwaves and unpredictable weather patterns have also caused short-term fluctuations in high street footfall.
Businesses that have invested well over the last few years in blending online and in-store shopping experiences for consumers are proving to deliver some of the strongest results. Whilst there are some early signs of recovery for consumer confidence following the conflict in the Middle East, overall spending power for consumers is down.
Disposable income remains tight, with further pain to come as fuel, energy and food inflation weigh on budgets. This places significant pressure on businesses reliant on big-ticket discretionary spend; an area we continue to monitor closely.
We continue to review cover on a case-by-case basis, with a strong emphasis on reviewing up-to-date confidential financial information. Demand is expected to remain challenging as we head into the second half of the year, so it is important that businesses focus on disciplined working capital and liquidity management if they are to succeed.
Retailers are also facing mounting cost pressures from increases in National Living Wage and National Insurance contributions making it even more difficult to preserve adequate profit margins
Mixed dynamics across key sub-sectors leaves the transport sector fragmented, with automotive performance challenged by new entrants and zero emission vehicle (ZEV) mandates; aerospace plagued by ongoing production delays; and long-standing hauliers still collapsing into administration.
Cost-cutting initiatives by global OEMs continue to reshape the UK automotive sector: from production line closures at Nissan’s Sunderland plant to Honda’s decision to shift to a commission-driven agency model. The latter limits both revenue and pricing power for selected dealers, at a time where competitors have reported triple-digit volume growth following the adoption of fast growing Chinese manufacturers. Freight and shipping channels continue to experience waves of volatility in the wake of ongoing geopolitical tensions with Hauliers seeing margins pinched from both ends as stiff competition drives revenues down while higher wage and fuel costs drive margins to unsustainably low levels. Aerospace, too, has faced soaring jet fuel costs in recent months and ongoing delays in engine body production lines but airline operators continue to show strong consumer ticket demand over the peak summer holiday season.
Despite challenges, our risk appetite remains strong but limitations are warranted on highly leveraged haulage operators; intensive fuel users without effective hedging arrangements in place; and single-franchise auto dealers exposed to shifts in OEM agency models. As inflationary pressures stabilise and consumer demand regains momentum, we should see improved performance across many of the industry’s sub-sectors, however expectations for this remain mid-to-long-term weighted.
Expectations for sub-sector performance improvements remain mid-to-long-term weighted.